If you’ve been trading Bitcoin or Ethereum in the US for the last few years, you know the feeling of holding your breath. Every week seemed to bring a new lawsuit from the SEC, a vague warning about whether your favorite token was a security, or a sudden change in how exchanges handled withdrawals. It was messy. But things shifted dramatically in 2025. The passage of the GENIUS Act and the push for the CLARITY Act didn’t just tweak the rules; they rewrote the playbook for who gets to trade what, where, and under whose watchful eye.
This isn’t just legal jargon. If you’re an investor, a trader, or someone running a small fund, these changes hit your wallet directly. We’re moving away from "regulation by enforcement"-where regulators sue first and ask questions later-to a system with clear lanes. Let’s break down what this actually means for your daily trading experience, without the law school fluff.
The End of the Gray Area: Three Buckets for Your Crypto
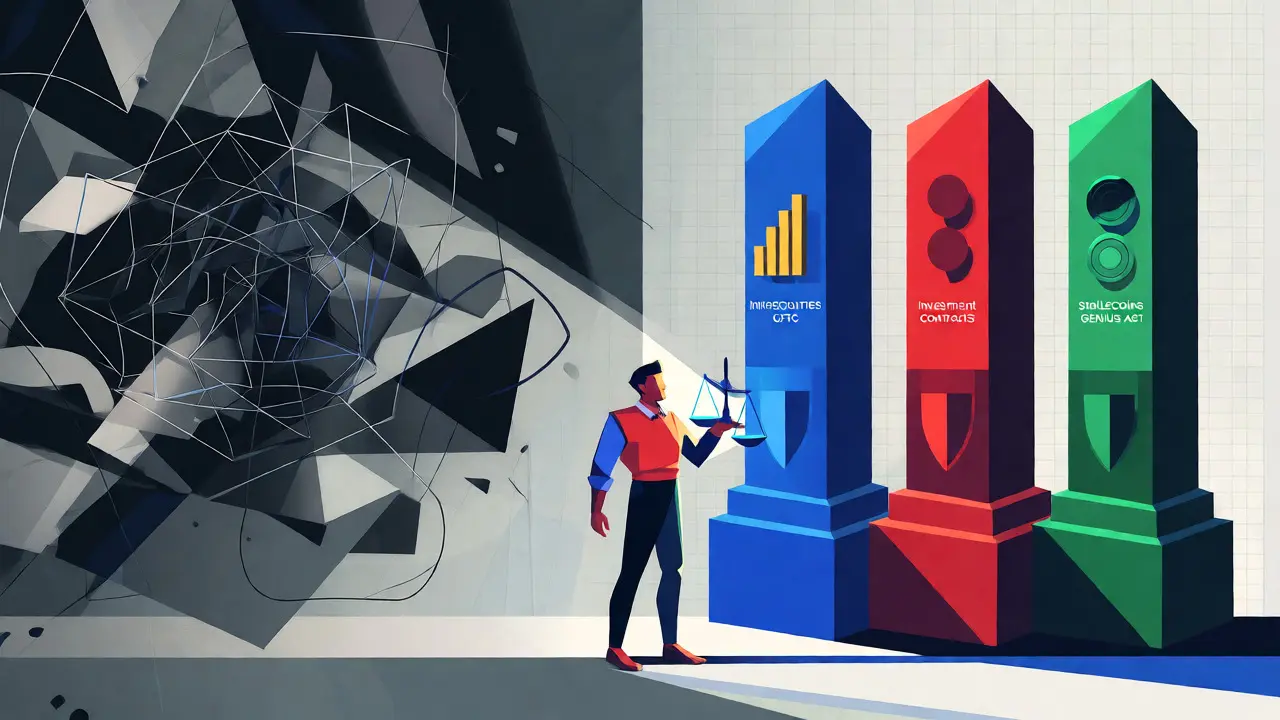
For over a decade, the biggest headache in US crypto was jurisdictional ambiguity. Is Solana a commodity? Is it a security? Does it depend on how much you buy? The proposed CLARITY Act solves this by creating three distinct categories. This is the core mechanic you need to understand because it dictates which agency regulates your assets.
- Digital Commodities: These fall under the Commodity Futures Trading Commission (CFTC). Think Bitcoin. They are treated more like gold or oil than stocks.
- Investment Contract Assets: These remain under the Securities and Exchange Commission (SEC). If a token promises profits based on the efforts of others, it’s likely here.
- Permitted Payment Stablecoins: Regulated under the GENIUS Act. These are USD-backed tokens used for payments, subject to strict reserve requirements.
Why does this matter? Because it removes the fear that a single regulatory shift could turn your entire portfolio into "unregistered securities." For traders, this means clearer tax reporting and fewer surprises when filing forms. The CFTC has historically been friendlier to spot trading of commodities than the SEC has been to securities, potentially opening up more venues for buying and selling major coins.
| Asset Class | Regulator | Key Requirement | Trading Venue Access |
|---|---|---|---|
| Digital Commodities | CFTC | Commodity exchange registration | Broker-dealers, ATSs, National Exchanges |
| Investment Contracts | SEC | Securities registration/exemption | Registered Broker-Dealers, Exchanges |
| Payment Stablecoins | GENIUS Framework | 1:1 Reserve backing & audits | Banking institutions, Licensed fintechs |
Stablecoins Get Serious: The GENIUS Act Impact
You probably use stablecoins every day if you trade. Whether it’s Tether (USDT) or USD Coin (USDC), they are the plumbing of the crypto world. In 2024, there were real fears that US regulators might ban or heavily restrict them due to reserve transparency issues. The GENIUS Act, signed in July 2025, stepped in to stabilize this chaos.
This act doesn’t regulate all crypto. It focuses specifically on USD-backed payment stablecoins. The rule is simple: issuers must hold high-quality liquid assets equal to the value of the stablecoins they issue. No more shady commercial paper reserves. For traders, this means two things. First, confidence in stablecoin pegs increases, reducing the risk of a de-peg event during market volatility. Second, traditional banks can now legally offer stablecoin services. Imagine withdrawing USDC directly from your Chase account. That integration is now possible, bridging the gap between your checking account and your Coinbase wallet.
However, compliance costs have gone up. Smaller stablecoin issuers may struggle to meet audit standards, potentially leading to market consolidation. You might see fewer obscure stablecoins and more dominance by large, regulated entities. This is good for safety but might limit some niche DeFi experiments that relied on unregulated dollar proxies.
How Trading Venues Are Changing
Before 2025, many crypto exchanges operated in a legal gray zone. Some registered as broker-dealers, others as money transmitters, and some tried to dodge regulation entirely. The new framework forces clarity. The legislation mandates that the SEC allow digital commodities and permitted stablecoins to be traded by registered broker-dealers and Alternative Trading Systems (ATSs).
This opens the door for traditional stockbrokers to offer crypto trading without losing their status. Firms like Robinhood or Schwab can now integrate Bitcoin trading more seamlessly because they aren’t forced to treat every transaction as a complex securities offering. For you, this means better customer service, FDIC insurance on cash balances (not necessarily on the crypto itself, but on the fiat side), and easier integration with retirement accounts.
But there’s a catch. Decentralized Finance (DeFi) platforms that don’t fit neatly into "broker" or "exchange" definitions face uncertainty. While the law helps centralized exchanges, fully decentralized protocols still lack a perfect home. If you’re using Uniswap or Aave, you’re largely outside this specific federal framework for now, though state-level laws are catching up.
What This Means for Institutional Money
Institutional investors hate uncertainty. For years, pension funds and hedge funds stayed on the sidelines because they couldn’t justify the regulatory risk to their boards. The 2025 acts changed that calculus. With clear custody rules-specifically allowing qualified state trust companies to hold crypto-the barriers to entry dropped significantly.
We saw a surge in institutional adoption following the launch of spot ETFs earlier in the decade, but the 2025 legislation provided the operational backbone. Asset managers can now advise clients on crypto with less fear of violating Rule 204A-1 (the code of ethics rule). If Bitcoin is classified as a commodity, employees at investment firms don’t need to pre-clear every tiny BTC purchase. This reduces administrative friction and makes crypto a standard part of diversified portfolios rather than a speculative outlier.
State Street Global Advisors and other giants are already launching actively managed crypto strategies. This trickle-down effect benefits retail traders too. More institutional volume usually means deeper liquidity and tighter spreads on major pairs like BTC/USD and ETH/USD.
Pitfalls and Practical Adjustments
Don’t assume everything is smooth sailing. Compliance is expensive. Small crypto businesses and startups often complain that the new reporting requirements favor big players. If you run a small trading bot or a niche exchange, you might find yourself spending more time on legal fees than on tech development.
Also, keep an eye on the distinction between "digital commodities" and "investment contracts." Just because a token started as a utility doesn’t mean it stays one forever. If a project team raises capital and promises returns, they might slip into the SEC’s bucket. Always check the latest guidance on specific tokens before making large moves. Don’t rely on old YouTube videos from 2023; the landscape has shifted.
Finally, remember that this is US law. If you’re trading on offshore exchanges not registered with the SEC or CFTC, you’re taking on different risks. The convenience of local regulation comes with the cost of restricted access to certain global assets. Some exotic altcoins available in Asia or Europe might not be listed on compliant US platforms yet.
Frequently Asked Questions
Does the Investment and Securities Act 2025 make all crypto legal?
Not exactly. It provides a clear legal framework for three specific categories: digital commodities, investment contract assets, and permitted payment stablecoins. Tokens that don't fit these categories may still face scrutiny or require individual legal analysis. It ends the era of blanket uncertainty but introduces structured compliance requirements.
Can I still trade on decentralized exchanges like Uniswap?
Yes, but the regulatory environment for DeFi is less defined than for centralized exchanges. The 2025 acts primarily target centralized intermediaries like broker-dealers and exchanges. DeFi protocols operate in a space where smart contracts replace brokers, so current laws apply differently, often focusing on the underlying asset classification rather than the platform itself.
How does the GENIUS Act affect my stablecoin holdings?
It requires issuers of USD-backed stablecoins to maintain high-quality liquid reserves and undergo regular audits. This increases the safety and reliability of major stablecoins like USDC and USDT. However, it may lead to the disappearance of smaller, less transparent stablecoins that cannot afford the compliance costs.
Will taxes change for crypto traders?
The acts themselves do not change tax rates, but they clarify asset classification. Digital commodities are generally treated similarly to other property for tax purposes, while securities may have different reporting nuances. Clearer classification helps reduce errors in tax filings, but you should always consult a tax professional for your specific situation.
Is Bitcoin considered a security under the new laws?
No. The legislative framework explicitly categorizes decentralized tokens like Bitcoin as digital commodities under CFTC jurisdiction. This distinguishes them from tokens sold as investment contracts, which fall under SEC oversight. This classification supports broader acceptance of Bitcoin as a commodity asset.
Next Steps for Traders
If you’re active in the markets, take ten minutes today to review your exchange choices. Ensure they are compliant with the new federal standards if you want the protection of US regulation. Check if your stablecoins are issued by entities adhering to the GENIUS Act reserves. And most importantly, stay informed about the final rulemakings from the SEC and CFTC. The laws are passed, but the detailed regulations are still being written. Adaptability is your best asset in this new, clearer, but still evolving landscape.